
The UK government has announced new workplace pension proposals designed to give private sector workers a more reliable income throughout retirement, with Pensions Minister Torsten Bell unveiling the plans on 4 November 2026. The Guided Retirement initiative aims to address a growing problem: millions of people are saving into defined contribution pensions but reaching retirement without a straightforward way to turn their savings into lifelong income. The proposals could change how pension providers support people approaching retirement, offering an alternative to withdrawing an entire savings pot.
What Moved
The central development is the government's plan to introduce Guided Retirement, requiring pension schemes to provide a default retirement income option for members approaching the end of their working lives.
Under the proposals, people who have spent years building a defined contribution (DC) pension pot will have the option of receiving a managed income throughout retirement rather than having to make complicated investment and withdrawal decisions themselves.
This represents a significant change in the government's approach to workplace pensions. Automatic enrolment successfully encouraged millions of workers to save, but the system has not always provided an equally straightforward route from accumulated savings to a dependable retirement income.
The government is also developing Retirement Collective Pension Schemes (RCPS), which would pool investment risks to help provide greater stability and support income payments throughout retirement.
Why It Moved
The proposals respond to a gap in the UK's defined contribution pension system. Over the past three decades, most private sector defined benefit schemes have closed. These traditional arrangements generally offered inflation-protected retirement income for life, leaving many newer workers dependent on pension pots whose eventual value and income depend on investment performance and withdrawal decisions.
Automatic enrolment has substantially expanded pension participation. According to the Department for Work and Pensions, nine in 10 eligible private sector employees are now saving, compared with four in 10 in 2012. However, most are building individual savings pots rather than guaranteed retirement incomes.
The government says the scale of the problem is visible in withdrawal behaviour. In 2025/26, approximately 46% of first-time pension pot accesses involved withdrawing the entire pot. Taking everything at once can leave people responsible for making their savings last for the remainder of their lives.
Minister for Pensions Torsten Bell said the government wanted to give private sector workers the option of a pension income lasting throughout retirement, including protection against rising living costs in many cases.
Financial Conduct Authority executive director Therese Chambers also backed the principle of providing more support, saying people should not have to navigate complicated pension decisions alone.

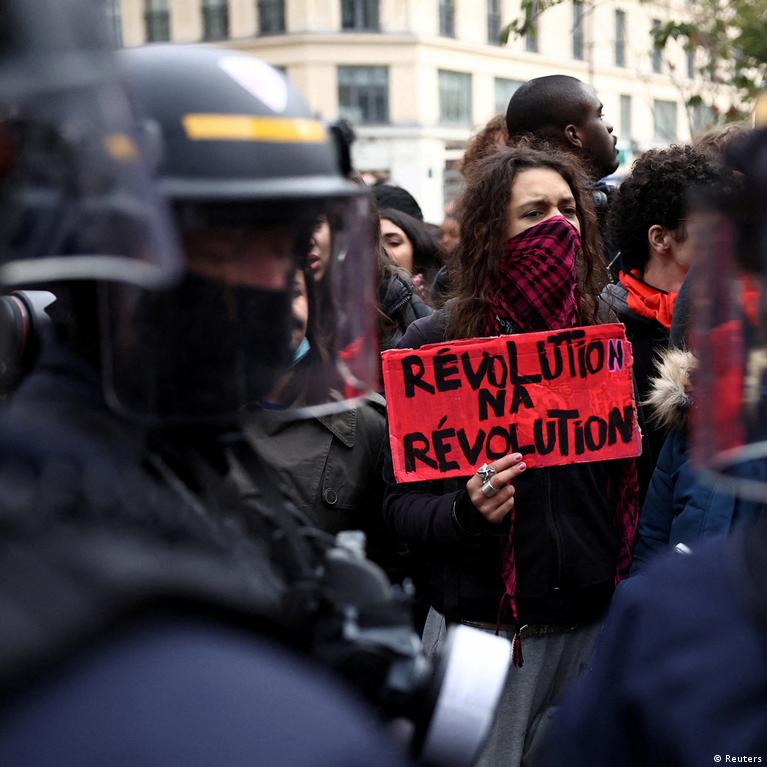
There is also a wider financial pressure behind the reforms. Falling birth rates and rising life expectancy are increasing the demands placed on public pension systems. France offers a particularly stark example: pensions account for 14% of its GDP, while public debt is approaching 120% of GDP. The country's attempts to increase the retirement age from 62 to 64 triggered major protests and strikes in 2023.
The UK operates a different model, relying more heavily on workplace and private pension savings. That gives British policymakers additional flexibility, but it does not remove the challenge of ensuring retirement savings last.
The Numbers That Matter

Several figures help explain why the government is changing its approach:
- 90%: The proportion of eligible private sector workers now saving into a pension through automatic enrolment, up from 40% in 2012.
- 46%: The proportion of first-time pension pot accesses involving a complete withdrawal in 2025/26.
- £12,548: The annual UK State Pension figure cited in the November 2026 reporting, rising to £13,036 next year.
- 66: The current UK State Pension age, scheduled to increase gradually to 67 by 2028.
- £15.9 billion: Individual contributions to personal pensions during the 2024/25 financial year, compared with £14.6 billion in the previous year.
These figures highlight two separate pressures. More people are saving for retirement, but a substantial proportion still need help deciding how to use those savings once they stop working. Meanwhile, the State Pension provides a foundation rather than a complete retirement income for most people.
Tax changes add another layer. From 6 April 2027, most unused pension funds and pension death benefits are scheduled to become subject to inheritance tax as part of the deceased person's estate. The government has also announced changes to pension death benefit taxation, including removing the additional tax consequence associated with certain payments made more than two years after the scheme administrator became aware of a member's death, for payments on or after 28 October 2026.
What Analysts Are Watching
The key question is whether the proposed default arrangements can deliver dependable retirement income without removing meaningful choice from savers.
Retirement Collective Pension Schemes are intended to pool risks and support managed income payments. Their practical performance, investment approach and ability to provide stability will matter to people deciding whether to use them instead of other retirement products.
There is also a broader affordability question. The experience in France shows how difficult pension reform can become when governments attempt to change established retirement expectations. The UK has a larger private pension system, but younger workers still need confidence that the State Pension and their personal savings will provide a reasonable foundation in later life.
Cross-party agreement will also matter. Heidi Karjalainen, a senior research economist at the Institute for Fiscal Studies, has argued that the UK's larger private pension pots provide more flexibility when governments consider changes to State Pension provision.
What Happens Next
The Department for Work and Pensions has published its Guided Retirement consultation jointly with the Financial Conduct Authority and The Pensions Regulator. It is seeking views on how default retirement arrangements should operate, how schemes should support members approaching retirement and how the framework can work in practice.
The consultation runs from 3 November to 22 December 2026. Pension providers and other interested organisations are being invited to contribute to the proposals.
The government has also published its response to the earlier policy consultation on Retirement Collective Pension Schemes, alongside draft regulations intended to allow these arrangements to operate as default options under Guided Retirement.
For workers, the immediate priority is understanding how their existing workplace pension works, how much they have accumulated and what income it could provide. The proposals are intended to improve the choices available at retirement, but they do not mean every saver will automatically receive a guaranteed income under the new arrangements immediately.
The wider direction is clear: the government wants pension providers to take more responsibility for helping people turn decades of contributions into sustainable retirement income. Whether the new framework delivers that outcome will depend on how the consultations translate into practical arrangements.
Frequently Asked Questions
What is the UK's Guided Retirement pension scheme?
Guided Retirement is a government proposal requiring pension schemes to offer default retirement income options to members approaching retirement. It aims to make it easier to convert defined contribution savings into an income that can last throughout retirement.
When will the new UK pension changes take effect?
The government launched its Guided Retirement consultation on 3 November 2026, with responses due by 22 December 2026. The consultation is intended to help shape the practical framework and does not itself mean all proposed arrangements are already operational.
What is a Retirement Collective Pension Scheme?
A Retirement Collective Pension Scheme is an arrangement designed to pool investment risks and provide a managed retirement income. The government intends to make these schemes available as potential default options under Guided Retirement.
Can I still withdraw my entire pension pot?
The government says choice will remain central to its approach. Savers who prefer a different retirement option will remain free to choose, while default arrangements are intended to help people who want more support managing their savings.
Will unused UK pension savings be subject to inheritance tax?
From 6 April 2027, most unused pension funds and pension death benefits are scheduled to be included in the estate for inheritance tax purposes. The change is already legislated for and will make pension beneficiary arrangements, wills and wider estate planning more closely connected.